
The unfunded trust is the most expensive estate planning mistake in Massachusetts — and the easiest one to check for yourself.
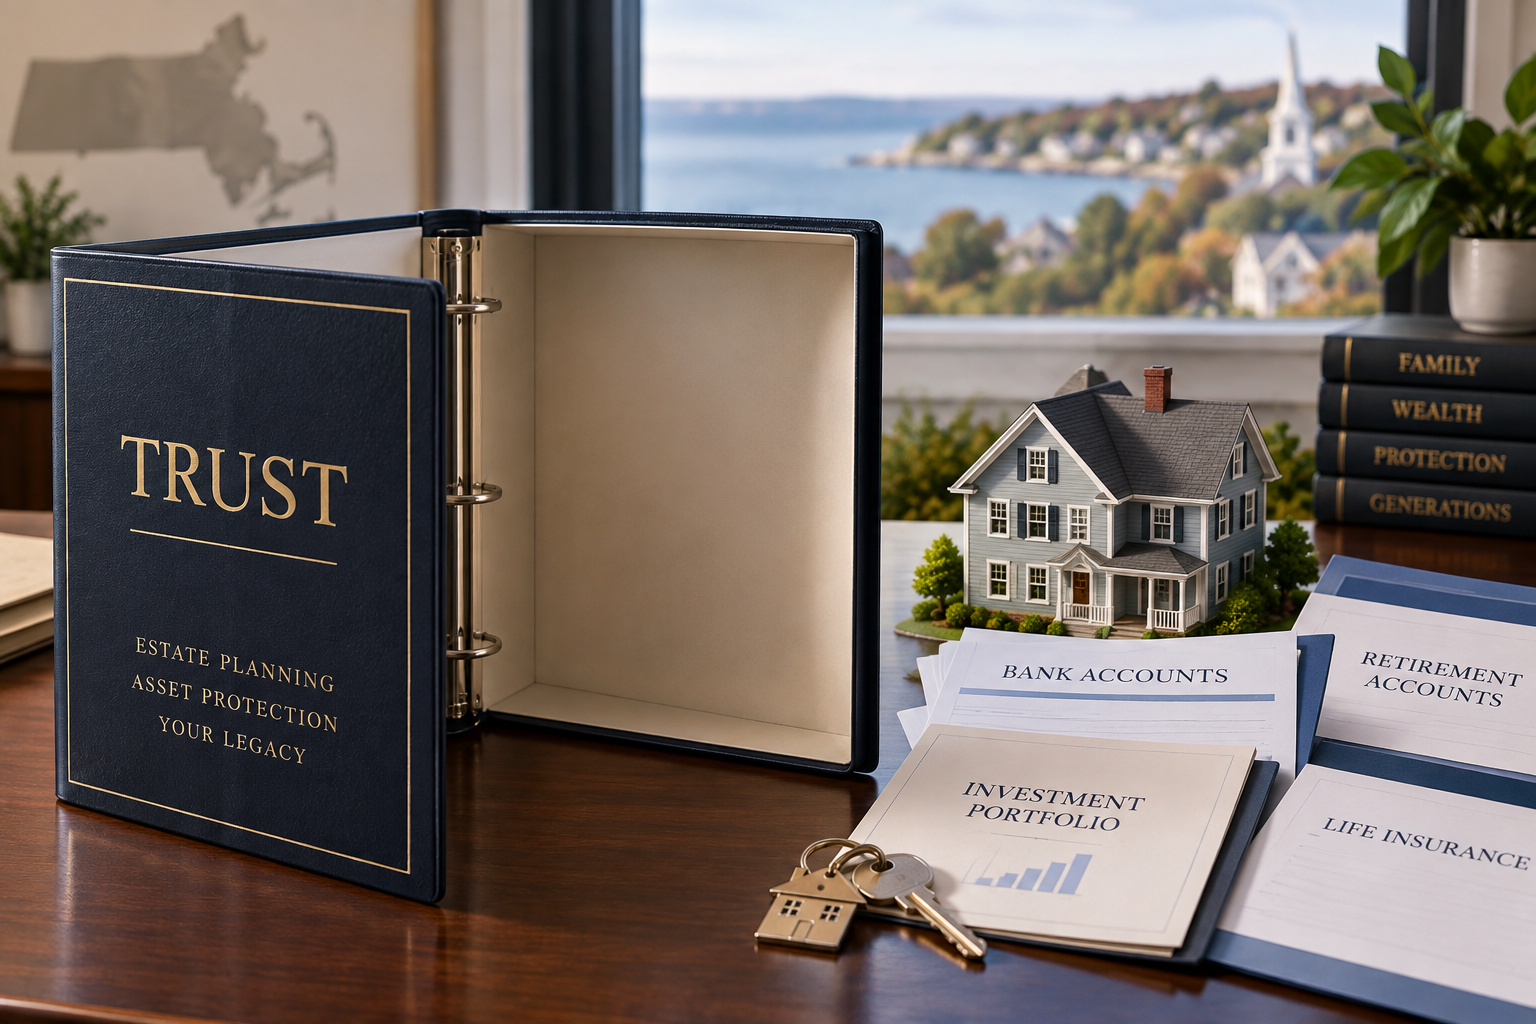
There is a binder in your house right now that cost you a few thousand dollars. There is a real chance it does not own anything.
If that is the case, it will not do the one job you bought it to do.
I am an estate planning attorney in Massachusetts, and this is the most common failure I see in plans that people paid real money for. It is almost never bad drafting. It is almost never the wrong kind of trust. It is a trust that was signed, filed in a binder, put on a shelf, and never filled.
The families who discover this discover it at the worst possible moment: after a death, in probate court, holding the binder.
Prefer to read? The full explanation continues below.
A trust is a container. Signing it does not fill it.
This is the whole idea, and once you have it, the rest follows.
Signing the trust document creates the container. That is all it does. It does not move your house, your bank accounts, or anything else into that container. Putting things inside is a completely separate act, done asset by asset, and it has a name: funding the trust.
Two steps. Most people only ever complete the first one, because the first one is the one that happens in the lawyer’s office with pens and a notary. The second one happens afterward, in the world, and requires somebody to actually do it.
What happens when a trust is never funded
Nothing happens — which is exactly the problem.
On the day you die, if the trust was never funded, your house is still owned by you. Your accounts are still owned by you. And every one of those assets goes through probate exactly as if the trust had never been written.
You paid to avoid a process your family is now going through anyway. The trust does not fail loudly. It just sits there, correctly drafted and completely inert.
Funding, asset by asset
Funding is not one action. It is a list, and someone has to work the list. What each item on that list requires depends entirely on the type of asset — and this is where people get lost, because the rules are not the same across categories. Some assets get retitled. Some should never be retitled.
Real estate
In Massachusetts this is usually the big one, because for most families the house is where the value is.
Moving a house into a trust means a new deed. And that deed has to be recorded at the registry of deeds for the county where the property sits. A deed that was signed and then filed in the binder is not a recorded deed, and an unrecorded deed does not accomplish what you think it accomplishes.
This is the one step not to do cheaply.
A deed done wrong can create title problems, tax problems, and problems with benefits eligibility that are considerably worse than the probate you were trying to avoid. Title defects surface years later, usually when the property is being sold or refinanced, and unwinding one costs far more than doing the deed correctly the first time. In Massachusetts a transfer of real estate into a trust can also interact with long-term care planning and with estate tax exposure. This is not a form to download and file.
Bank and brokerage accounts
These are more straightforward. You retitle the account into the name of the trust. The bank or brokerage has a process for this, it is usually routine, and it usually requires either a copy of the trust or a certificate summarizing it — a short document that proves the trust exists and identifies the trustee without disclosing the rest of your plan.
Expect to do this account by account, at each institution. There is no central switch.
Retirement accounts — the counterintuitive one
Your 401(k). Your IRA.
You generally do not retitle these into a trust, and doing so can trigger consequences you very much do not want. Retirement accounts pass by beneficiary designation instead. So for these, the document to check is not a deed and not an account title. It is the beneficiary form.
Whether a trust should ever be named as the beneficiary of a retirement account is a genuinely technical question. Sometimes it is the right answer. Often it is not. The analysis depends on who your beneficiaries are, their ages and circumstances, how the trust is written, and how the account is taxed on the way out. Treat any blanket rule you read online about this — in either direction — with suspicion.
Life insurance and annuities
Same shape as retirement accounts. These pass by beneficiary designation, not by retitling. The form controls.
Everything else
Vehicles, business interests, partnership shares, and valuable personal property each have their own mechanics, and closely held business interests in particular often have transfer restrictions written into the operating agreement that have to be worked around. These items are usually where a funding list stalls, because none of them have an obvious process the way a bank account does.
The pour-over will is a net, not a shortcut
Most trust-based plans include a pour-over will. Its job is to catch whatever you forgot and direct those leftovers into the trust.
That is a genuine safety net, and you should have one. But understand what it costs.
Anything the pour-over will catches goes through probate first, and then lands in the trust. So it protects where the asset ends up. It does not protect your family from the court process. If the thing being caught is your house, you have effectively bought a trust and gotten probate anyway.
A pour-over will is insurance against forgetting a small account. It is not a substitute for funding.
Two things you can check yourself this week
You do not need to hire anyone to find out whether you have this problem. Two checks, about ten minutes total.
1. Read your deed
Massachusetts registries of deeds maintain searchable records online at masslandrecords.com. Select your county, search by your name or your property address, and pull up the most recently recorded deed for the property.
You are looking at exactly one line: whose name is on it.
If it lists your name individually, and not the name of your trust as trustee, then the house is not in the trust — regardless of what is in the binder. If it lists the trust, the deed was recorded and that piece is done.
One caveat: a few Massachusetts counties run separate portals, and registered (Land Court) property can display differently from recorded land. If what you find does not look like a clear answer, that is a question worth asking rather than guessing at.
2. Read every beneficiary designation
Log in to every retirement account and every life insurance policy you have and read the current beneficiary designation on the screen.
Not what you remember choosing. Not what you told someone you would change. What the form says today.
People find ex-spouses on these forms more often than you would believe. They find deceased parents. They find blanks. A beneficiary designation overrides your will and your trust for that account, so a stale form quietly rewrites your plan for that asset, and nobody discovers it until the claim is filed.
If both of those checks come back clean, you are in good shape. If either one surprises you, that is worth fixing — and it is usually fixable.
What not to do yourself
Checking is safe. Fixing is not always.
Reading public records and your own beneficiary forms carries no risk. Preparing and recording a deed to your own home does, for all the reasons above. If your deed check comes back showing the house in your individual name, the right next move is a conversation, not a form.
⬇ FREE DOWNLOAD: The Trust Funding Checklist
A simple checklist covering every major asset category, with space to write down what you find. It is the same list I use when a client brings me a binder and asks whether it is doing anything.
Print it, spend ten minutes with it, and you will know more about your own plan than most people ever find out.
When to have someone open the binder
What an article cannot tell you is whether your particular trust should hold your particular house. In Massachusetts that answer interacts with long-term care planning and with the estate tax in ways that are specific to your family, your assets, and your timeline.
If you want someone to open the binder, pull the deed, and tell you what you actually have, that is what a consultation is for. Bring the binder and bring the completed checklist — with those two things on the table, the conversation is a short one.
Botelho Law Group — Free Consultation
- Phone: 508-500-1551
- Schedule online: Request a consultation
- Estate Planning & Probate: Massachusetts estate planning and probate
- Asset Protection: Massachusetts asset protection
This article is general information about Massachusetts law and is not legal advice. Reading it does not create an attorney-client relationship. Laws change and every situation is different. Consult a licensed attorney about your own circumstances.