
What if the Massachusetts home you’ve worked decades to pay off becomes a frozen asset for over a year the moment you pass away? For many families, the realization that a simple will doesn’t stop the state from intervening comes too late. You likely want your property to remain a private family matter, yet without specific planning, your estate could be stalled in the Bristol County Probate and Family Court while legal fees and public disclosures mount.
Establishing a revocable living trust Massachusetts is no longer just a strategy for the wealthy; it’s a necessary safeguard for any homeowner. We understand the anxiety of watching home equity vanish into nursing home costs or seeing a legacy tied up in the complexities of the MUTC. This 2026 guide will show you how to maintain total control of your assets while you’re alive and ensure a seamless, private transfer to your heirs. We’ll explore how to maximize your protections under the MA Homestead Act and navigate the updated 2026 MassHealth look-back rules to keep your equity where it belongs.
Key Takeaways
- Learn how to bypass the year-long Bristol County probate process and keep your estate distribution entirely private.
- Discover why a revocable living trust Massachusetts is the most effective tool for maintaining control over your home while ensuring a seamless legacy transfer.
- Understand the critical step of re-filing your Massachusetts Homestead Act declaration after funding your trust to protect up to $500,000 in equity.
- Identify the specific 2026 legal requirements under the Massachusetts Uniform Trust Code to ensure your documents stand up to scrutiny.
- Explore the “Protective Advocacy” model that builds a secure legal fortress around your primary residence and financial assets.
Why a Revocable Living Trust is Essential for MA Homeowners in 2026
A revocable living trust is a sophisticated legal entity designed to hold your real estate and personal assets while you maintain absolute control. In 2026, the Massachusetts real estate market has reached unprecedented heights, with home equity levels surging across the Commonwealth. This growth means that even modest family homes now push many estates into complex territory. What many families previously considered a simple estate is now a high-stakes legal matter that requires more than a basic will.
Relying on the default provisions of the Massachusetts Uniform Probate Code (MUPC) for DIY estate planning is a significant risk. While the MUPC provides a framework for asset distribution, it’s often a rigid system that fails to account for specific family dynamics or rapid equity growth. The primary objective for any homeowner should be keeping the family residence out of the public, slow, and expensive probate court system. By establishing a revocable living trust Massachusetts residents can ensure their most valuable asset remains a private family legacy rather than a public court record. This proactive approach follows the foundational principles of U.S. trust law, which prioritizes the intent of the property owner while providing a clear structure for asset management.
Bypassing the Massachusetts Probate Process
Probate in Bristol County is notorious for its procedural bottlenecks. It’s common for even uncontested estates to take 12 to 18 months to finalize through the court system. During this period, your heirs are often left in a state of legal limbo. They may be unable to sell, refinance, or properly maintain the property while the case sits on a docket. The hidden costs of probate, often called the “Probate Tax,” include cumulative court filing fees, mandatory publication notices, and the ongoing legal representation required to navigate the court’s strict requirements. A trust removes these hurdles entirely. It allows your successor trustee to take immediate action, providing your family with the housing security they need without waiting for a judge’s signature.
The Massachusetts Uniform Trust Code (MUTC) Advantage
The Massachusetts Uniform Trust Code, codified under Chapter 203E, serves as the modern statutory framework that ensures your trust remains flexible and legally enforceable. This code specifically protects settlors by allowing you to serve as your own trustee, maintaining total autonomy over your home and financial accounts. You don’t lose ownership in a practical sense; you simply change the legal capacity in which you hold the title. Because the trust is fully revocable, you retain the power to amend or dissolve the entity as your family or assets evolve. This ensures your estate plan stays as dynamic as the 2026 legal landscape requires.
Revocable Living Trust vs. Will vs. Life Estate
A common misconception among homeowners is that a “Simple Will” provides a direct path for asset transfer. In reality, a will is merely a set of instructions for the probate court. To transfer a deed in Massachusetts, a will must be filed, verified, and administered through a public court process that often lasts over a year. This is the “Simple Will” trap. It creates a mandatory appointment with a judge rather than avoiding one. Without a trust, your heirs cannot legally sell or refinance the family home until the court grants authority, a delay that can be financially devastating during market shifts.
Privacy is another critical differentiator. When you file a will, it becomes a public record available for anyone to view. Conversely, a revocable living trust Massachusetts remains a private document kept within our professional files. This confidentiality prevents predatory creditors or curious parties from scrutinizing your family’s financial legacy. While the upfront cost of a trust is higher than a basic will, it is a strategic investment. Standard probate administration expenses in the Commonwealth frequently range from $3,500 to over $15,000 for complex cases. By opting for a trust, you effectively prepay for a seamless transfer, saving your family significant time and money later.
The Life Estate Alternative: A Cautionary Note
Many residents use a Life Estate to qualify for MassHealth, but this strategy carries a significant “Loss of Control” risk. When you deed a remainder interest to your children, you cannot sell, refinance, or mortgage the property without their written consent. If a child faces a divorce, bankruptcy, or lawsuit, your home’s title could be jeopardized by their personal legal troubles. A revocable trust offers superior flexibility. It allows you to retain total authority over the property title while you’re alive, ensuring you can change your mind as family dynamics evolve. If you’re concerned about maintaining autonomy, our firm can help you evaluate your title options.
Asset Protection and Incapacity Planning
A will only takes effect upon death, leaving a dangerous gap if you become ill or injured. A trust manages your assets the moment you sign it, which is vital for incapacity planning. By working with a power of attorney lawyer Fall River, you can create a comprehensive shield for your estate. You appoint a Successor Trustee who can step in to handle property taxes, insurance, and maintenance without a court-appointed conservatorship. This proactive structure keeps your private matters out of the Bristol County Probate and Family Court, ensuring your home remains protected even if you cannot manage it yourself.
Strategic Asset Protection for your Massachusetts Primary Residence
Your primary residence is likely your most significant financial asset. In Massachusetts, the Homestead Act provides a robust shield, protecting up to $500,000 of your home’s equity from most creditor claims. However, a common misconception is that this protection remains static once you establish a trust. When you transfer your property title into a revocable living trust Massachusetts, you effectively change the legal owner from yourself to the trust entity. This transition requires a meticulous update of your legal filings to maintain your protective status.
While a revocable trust is the ultimate tool for probate avoidance, it’s vital to understand its limitations regarding long-term care. Under the current 2026 MassHealth regulations, assets held in a revocable trust are still considered countable assets because you maintain the power to revoke the trust and access the equity. The 2026 expansion of the five-year look-back period to include home-based care services makes this distinction even more critical for families planning their future care. While a revocable trust avoids probate, an irrevocable trust is typically required for Medicaid asset protection.
Maximizing Your Declaration of Homestead
Massachusetts provides an automatic homestead protection of $125,000 for all homeowners. To secure the full $500,000 protection, you must file a formal Declaration of Homestead with the Bristol County Registry of Deeds. If you move your home into a trust, you must re-file this declaration. Failure to do so can leave your equity exposed to creditors. The registry has specific requirements for trust-owned property, and ensuring your documentation aligns with these standards is critical for maintaining your safety net.
Real Estate Funding: Moving the Deed
The most frequent error in estate planning is the failure to “fund” the trust. A trust is like a vault; it only protects what you put inside. To fund your trust, you must record a new deed at the registry that transfers the property from your name to the Trustee of your trust. This process often involves a Trustee’s Certificate, governed by MGL c. 184, § 35, which provides third parties with evidence of your authority to manage trust property. Most homeowners worry that this transfer will trigger a mortgage acceleration clause. Under federal law, lenders generally cannot prevent you from transferring your primary residence into a revocable trust, allowing you to secure your estate without disrupting your financing.
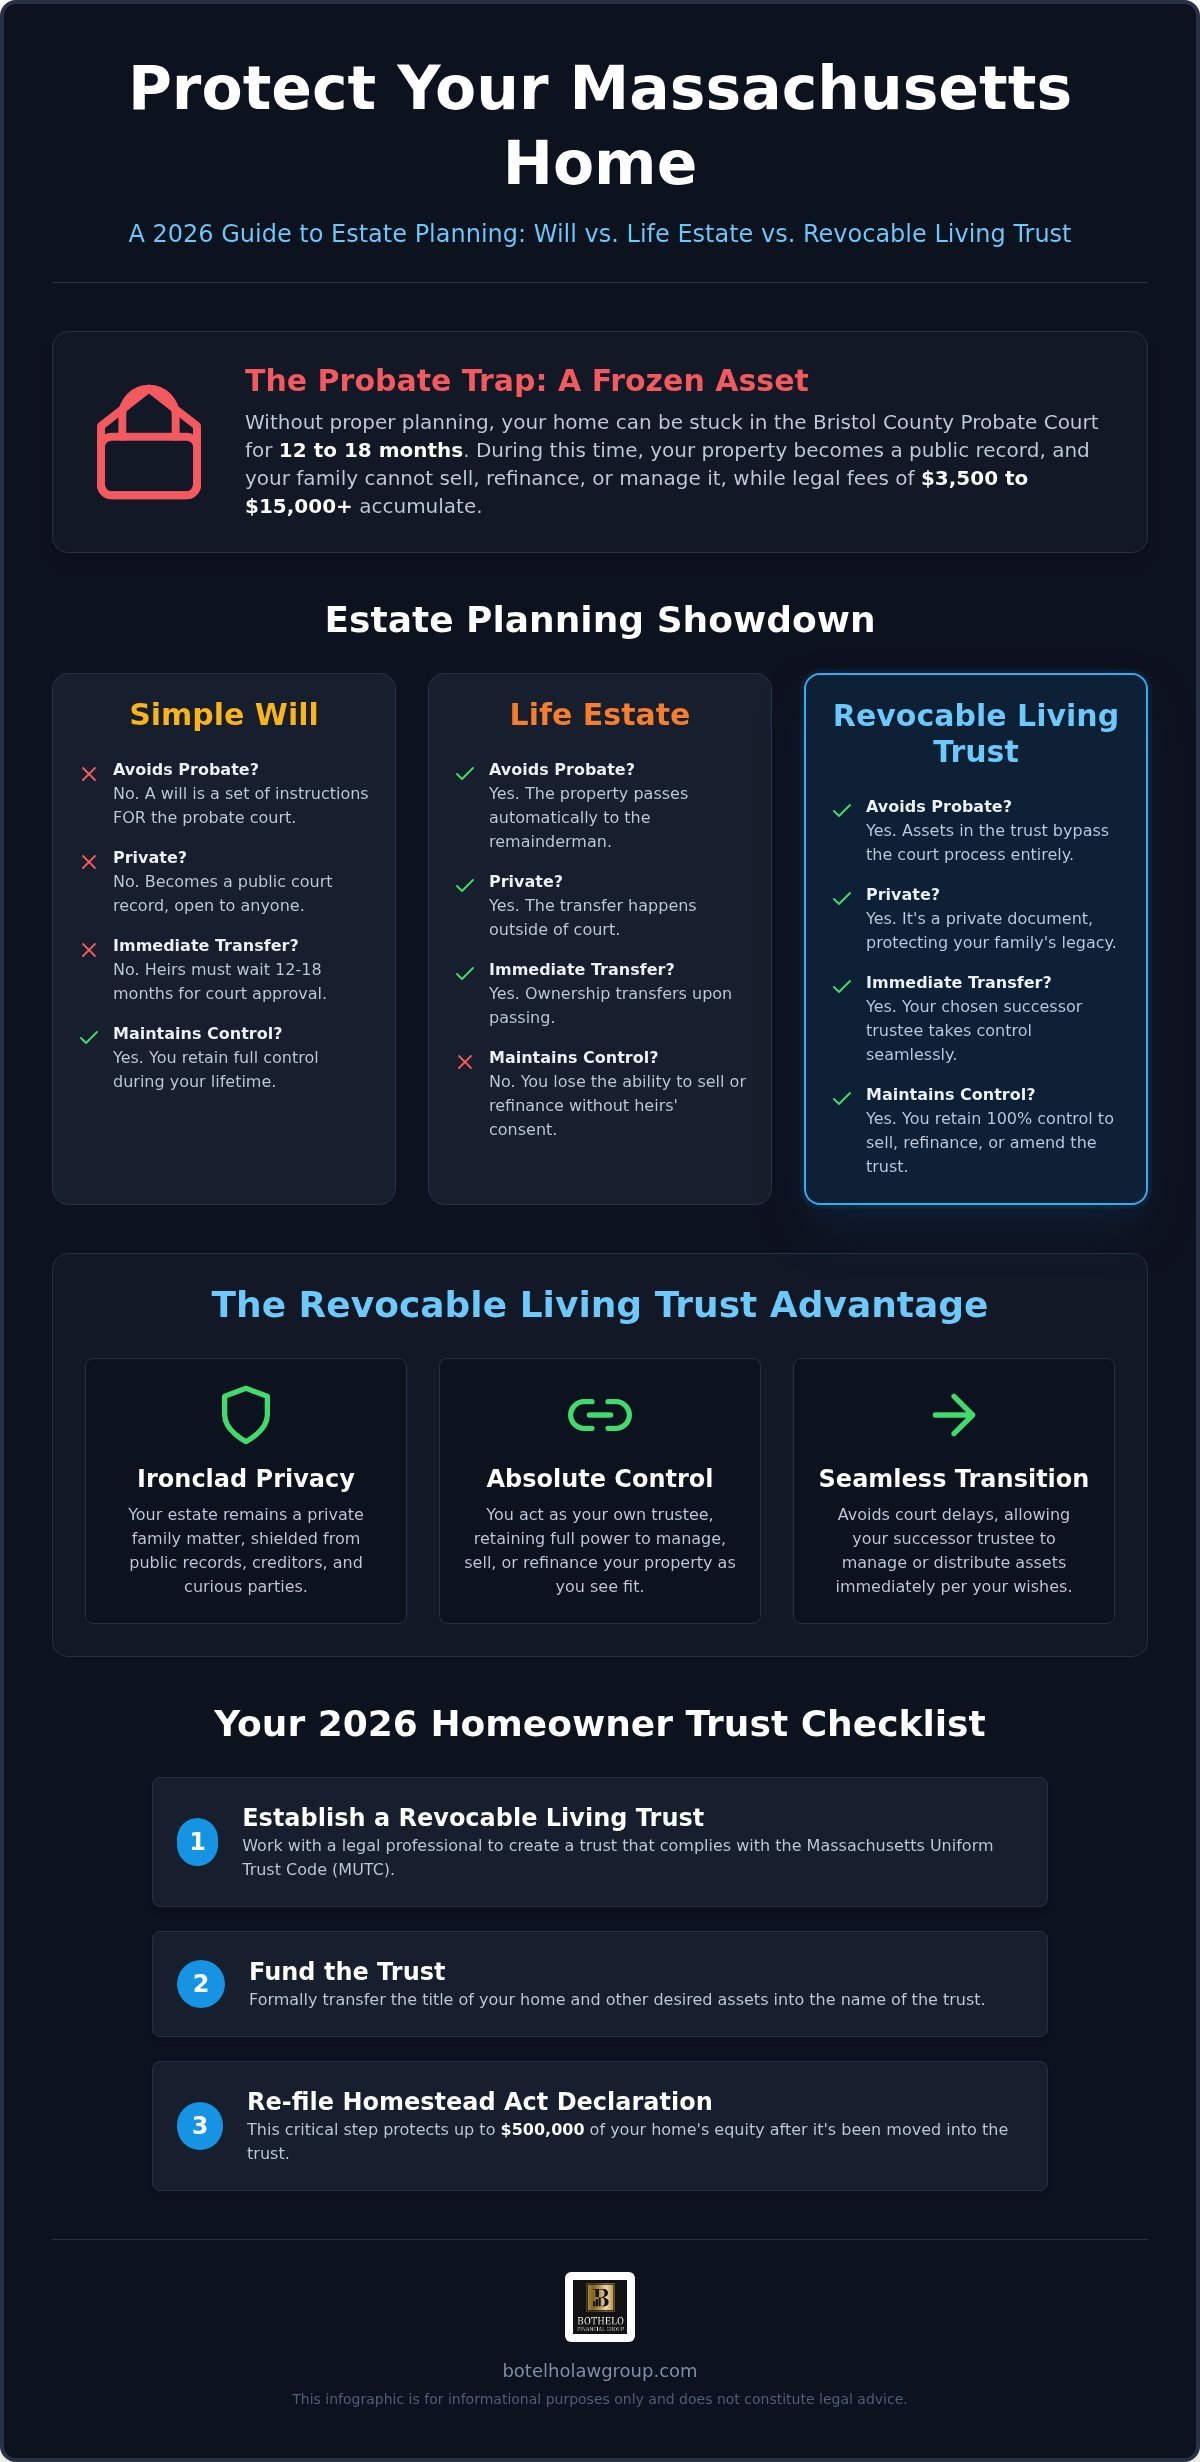
The 2026 Massachusetts Homeowner Trust Checklist
Establishing a revocable living trust Massachusetts homeowners can rely on requires a systematic approach. It’s not enough to simply sign a document; you must ensure every piece of your estate is legally aligned with the trust’s structure. Given the 2026 real estate market, where home equity often exceeds traditional expectations, a methodical transition is the only way to guarantee your legacy remains secure. Following a structured sequence prevents the administrative gaps that often lead to probate court intervention.
- Step 1: Conduct a high-equity valuation. Determine the current market value of all Massachusetts real estate to assess potential tax implications and insurance needs.
- Step 2: Draft the trust according to MUTC standards. Ensure the document complies with the Massachusetts Uniform Trust Code to maintain maximum flexibility and legal standing.
- Step 3: Execute a Quitclaim Deed. Formally transfer the property title from your individual names to the trust entity.
- Step 4: File the updated Declaration of Homestead. Record this with your local Registry of Deeds immediately after the deed transfer to protect your equity.
- Step 5: Consolidate support documents. Update your “pour-over” will and powers of attorney to ensure they reference the trust correctly.
Deed Review and Title Coordination
Before transferring your property, we must identify your current holding status. Many married couples hold property as “Tenants by the Entirety,” a specific designation in the Commonwealth that offers unique creditor protection. Transitioning to a trust simplifies the eventual transfer of property between spouses and to heirs, but it must be done without creating gaps in your title history. A critical, yet frequently overlooked, step is notifying your title insurance and homeowners insurance providers of the transfer. Failure to update these policies can lead to a denial of coverage if a claim arises after the home is moved into the trust. If you’re ready to secure your property, contact our team for a deed assessment.
Post-Execution Maintenance
A trust is a living document that must evolve with your life. We recommend reviewing your estate plan every three to five years, or whenever you experience a significant life event such as a new property purchase, a change in family structure, or shifts in Massachusetts tax law. Regular audits ensure your trust remains in full compliance with updated MGL statutes and continues to provide the protection you expect. For a professional review of your existing plan, consulting an estate planning lawyer Fall River MA can provide the precision needed to keep your legal fortress intact.
Protective Advocacy: Why Botelho Law Group for Your MA Trust
Botelho Law Group operates on a principle of protective advocacy. We recognize that for many homeowners, a revocable living trust Massachusetts is the single most important document they’ll ever sign. It isn’t just about drafting paperwork; it’s about building a legal fortress that shields your equity from unnecessary court intervention and predatory claims. Our firm provides a results-oriented approach that prioritizes the stability of your family’s future. By choosing a full-service firm, you gain the advantage of attorneys who understand the intersection of state probate laws and the specific 2026 federal tax implications. You’ll work directly with senior attorneys who specialize in Massachusetts asset protection, ensuring your strategy is both sophisticated and precise. This direct access ensures that your specific concerns aren’t lost in a large firm’s bureaucracy but are instead handled with the individual seriousness your case deserves.
Our Local Bristol County Expertise
Our deep roots in Fall River and Bristol County provide a distinct advantage for local residents. We maintain a constant presence in the Bristol County Registry of Deeds and the local Probate Courts, allowing us to navigate their specific procedural requirements with efficiency. Whether you’re in Fall River, New Bedford, or Somerset, you benefit from a partner who understands the local real estate market and the unique risks facing homeowners in our region. We don’t just provide generic advice; we offer localized expertise that reflects the specific property values and legal climate of Southeastern Massachusetts. This regional focus means we’re already familiar with the challenges you face, from local property tax nuances to the specific tendencies of the Bristol County court system.
Schedule Your Comprehensive Consultation
Your journey toward a secure legacy begins with a comprehensive strategy session. During this consultation, we analyze your specific real estate holdings and financial goals to determine the optimal trust structure for your family. Our process doesn’t end when the trust is signed. We guide you through the critical funding phase, ensuring your deeds are correctly recorded and your Declaration of Homestead is properly filed to maximize your $500,000 equity protection. We believe that a plan is only as good as its execution, which is why we handle the technical recording details that many other firms leave to the client. Don’t leave your home’s future to the state’s slow and public probate system. Take control of your legacy today by scheduling a session with our dedicated legal team to build a plan that lasts. For a professional review of your current holdings or to start a new plan, consult an estate planning lawyer Fall River MA to ensure your assets are fully protected.
Securing Your Legacy for 2026 and Beyond
Managing the complexities of the Massachusetts Uniform Trust Code requires a strategist who understands the high stakes of homeownership. A revocable living trust Massachusetts is the most effective tool to remove your primary residence from the public probate system and ensure your family avoids the costly delays of the Bristol County courts. You’ve worked hard to build your home’s equity; don’t let administrative bottlenecks or outdated legal frameworks drain that value away. Our approach focuses on results, ensuring your Homestead Act protections are fully integrated with your trust structure so your assets remain secure.
Botelho Law Group serves as your dedicated Fall River estate planning specialists. We provide protective advocacy for homeowners, utilizing our deep expertise in MUTC and MUPC compliance to build a legal fortress around your assets. It’s time to take a proactive stance against legal uncertainty and secure what you’ve built. Secure your Massachusetts home today: Contact Botelho Law Group for a Trust Consultation. Your family’s peace of mind is the ultimate return on this strategic investment, and we’re here to guide you through every step of the process.
Frequently Asked Questions
Do I need a revocable living trust if I only own one home in Massachusetts?
Even if you only own a single primary residence, a revocable living trust Massachusetts is highly beneficial to avoid the mandatory probate process. In the Commonwealth, real estate held in an individual’s name must pass through the court system before a deed can be transferred to heirs. This process often lasts over a year. A trust allows for an immediate transfer of the property title, saving your family from public court proceedings and significant administrative delays.
Does a revocable trust protect my home from a lawsuit or creditors in MA?
A revocable trust does not provide asset protection against personal lawsuits or creditors because you maintain total control over the assets. Since you can revoke the trust at any time, the law views the property as yours. To protect your home’s equity from creditors, you must rely on the Massachusetts Homestead Act or consider an irrevocable trust structure. Our firm helps you coordinate these tools to maximize your security against potential legal claims.
Will putting my house in a trust affect my mortgage or property taxes?
Transferring your home into a revocable trust typically has no impact on your mortgage or property taxes. Under federal law, specifically the Garn-St. Germain Act, lenders are prohibited from triggering “due on sale” clauses for transfers of a primary residence into a revocable trust. Additionally, your local property tax assessments and exemptions remain unchanged. You continue to pay taxes exactly as you did before the transfer, ensuring your financial obligations remain steady.
What is the difference between the MUTC and the MUPC for homeowners?
The Massachusetts Uniform Trust Code (MUTC) and the Massachusetts Uniform Probate Code (MUPC) serve different legal functions. The MUTC provides the rules for creating and administering trusts, offering flexibility for trustees and protection for beneficiaries. The MUPC governs the court-supervised process for wills and estates. While the MUPC dictates how a probate case moves through the court, a properly drafted trust utilizes the MUTC to bypass that entire court-dependent system.
Can I still sell my house if it is held in a revocable living trust?
You retain absolute authority to sell, refinance, or lease your home once it is held within a revocable trust. As the trustee, you exercise the same rights you had as an individual owner. The trust simply changes the capacity in which you hold the title. There are no additional hurdles or third-party approvals required for a sale, provided your trust documents are drafted to meet current Massachusetts real estate standards and title requirements.
How much does it cost to set up a revocable living trust in Massachusetts?
The investment required to establish a revocable living trust Massachusetts depends on the complexity of your estate and the specific goals of your family. Professional fees typically cover the initial strategy consultation, document drafting, deed preparation, and the filing of a new Declaration of Homestead. While there is an upfront cost for these legal services, it is significantly lower than the cumulative court fees and legal expenses your heirs would face during a lengthy probate administration.
Does a revocable trust help me qualify for MassHealth/Medicaid?
A revocable trust does not shield your home from MassHealth or Medicaid “countable asset” limits. Because you have the power to revoke the trust and access the equity, the state considers these funds available to pay for your care. If your primary goal is long-term care planning or protecting assets from the five-year look-back period, an irrevocable trust is the more appropriate legal instrument. We can evaluate your specific situation to determine which structure fits your needs.
What happens if I forget to move my deed into the trust?
Failing to record a new deed is the most common mistake in estate planning, often resulting in an “unfunded” trust. If the deed remains in your individual name, the trust has no legal authority over the property. Upon your passing, the home would still require a probate court proceeding to transfer the title. While a “pour-over” will acts as a safety net to move the home into the trust, it cannot bypass the probate process you intended to avoid.